The $4 Million Vending Machine “Investment” That Was Never Really an Investment
A few months ago, I wrote about fruit juice vending machine franchises after attending FLA 2025, and why I personally wouldn’t put my money into one. Franchised or not, vending machines have stayed in the news for a very different reason since then, and this time the numbers are a lot bigger.
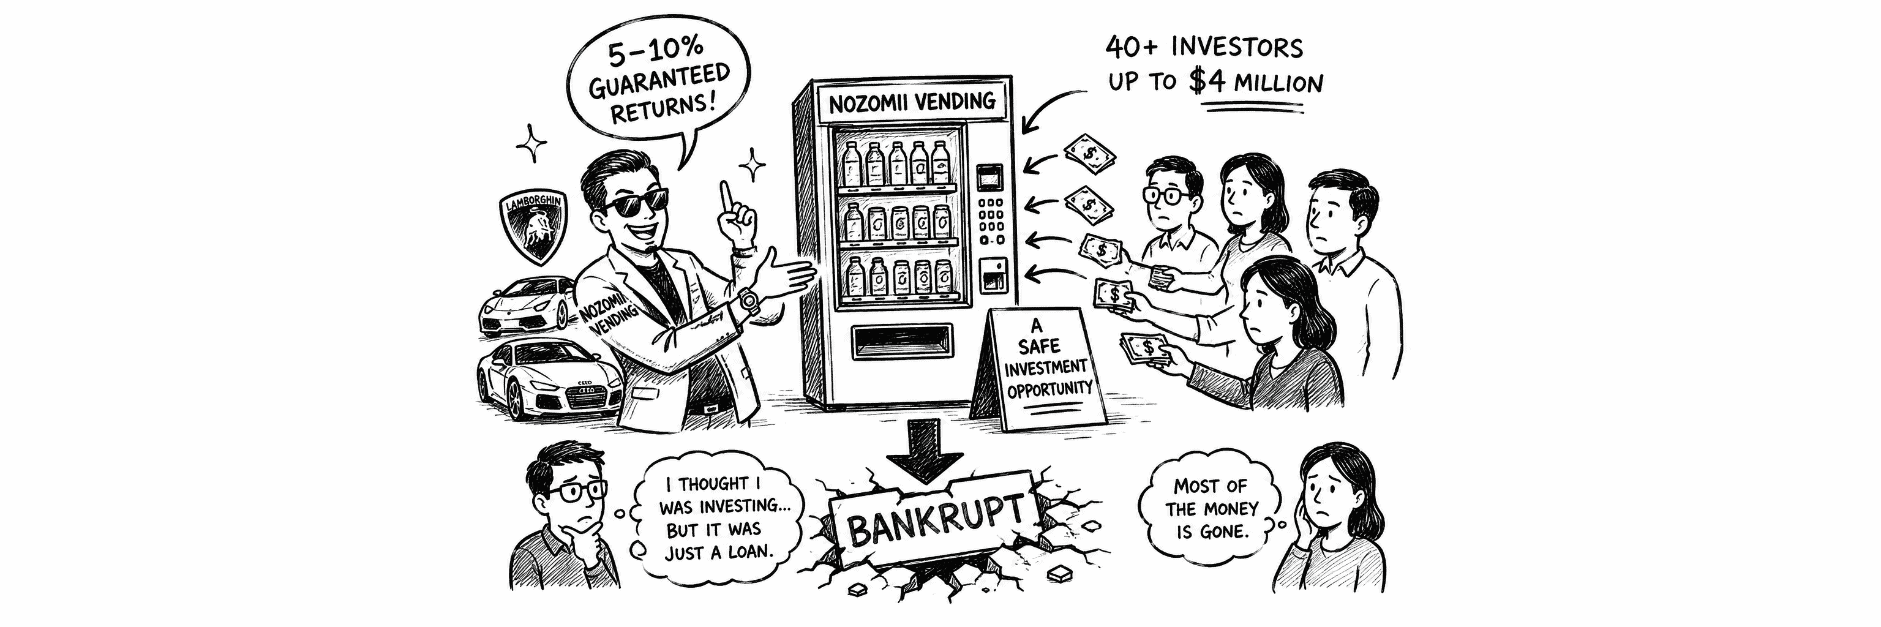
In a recent new article, Lim Jian Bin, a former private-hire driver who rebranded himself online as “Takeshi Lim,” met potential investors driving a Lamborghini, then an Audi R8, decked in branded clothes with a luxury watch on his wrist. Over three years from 2023, more than 40 investors put up to $4 million into his company, Nozomii Vending, and a related industrial property scheme, on the promise of 5 to 10 per cent guaranteed annual returns. On 14 July 2026, Lim was declared bankrupt. Most of that money is gone.
Here’s the detail that stopped me. One of the investors who lost the most, Kevin Lin, is himself a financial adviser. He put in $484,300, including $291,322 he borrowed from banks specifically to invest more.
And I think most people were talking about this financial adviser than what Lim Jian Bin did.
I could see why. This wasn’t a case of an unsophisticated victim who didn’t know better. It’s proof that “financial adviser” is a job title describing what products someone is licensed to sell you financial products, but it’s not a guarantee of good judgement whether this person has the right expertise to help you make good informed financial decisions.
We can also see that once greed takes hold of you, it can switch off the exact scrutiny a trained financial professional should be applying.
Every week, I’ll be sharing practical tips and invaluable knowledge to guide you on your path to financial independence.
You Weren’t Investing. You Were Lending
Let’s look closely at what the 40-plus people who gave Lim money actually received. It doesn’t seem like they received an ownership share of a vending machine. Neither did they receive any equity in the business.
A fixed monthly payment on a schedule, in exchange for handing over cash.
That’s a loan, not an investment, no matter what word everyone involved used to describe it.
Some may even call it project financing.
This distinction isn’t academic. Once Lim was declared bankrupt, a statutory moratorium kicked in immediately. Individual creditors can no longer take action to recover what they’re owed; only the official assignee or a trustee can now deal with his assets. Kevin was lucky to recover $100,000 through a debt recovery agency in the narrow window just before the bankruptcy order was made. Everyone else is now an unsecured creditor waiting in line, the same position you’d be in if you lent a friend money on a handshake.
If you can’t point to what you actually own, a vending machine, shares, a title deed, you’re not investing. You’re lending, and you should price that risk accordingly.
No MAS Licence Means No Protection
When I first looked into this, my instinct was that Lim’s arrangement should have needed the same authorization as any pooled fund, a Collective Investment Scheme (CIS). It’s worth being precise about why that’s not quite the right box, because the actual answer is more interesting after I research into the details.
A CIS has a specific legal shape:
- Participants have no day-to-day control over the property
- Their contributions are pooled together
- Crucially, the profits or income are pooled too, so everyone shares proportionally in how the whole fund performs
Think of a unit trust, where your returns rise and fall with everyone else’s, based on the fund’s overall performance. That’s not what Lim was offering.
Each investor signed their own agreement with their own fixed rate, Lin’s was 10% a year over four years, the industrial property arrangement was 5% over three years, paid to them individually regardless of how anyone else’s money performed, or how the underlying machines were actually doing.
That’s not a shared pool. That’s a stack of individual, bilateral promises.
But structuring it this way doesn’t get you out of MAS’s rules, it just points you at a different rule.
Any invitation to lend money to a company in exchange for a return is treated in Singapore as an offer of debentures, which is itself a type of security. Offering securities to the public here normally requires a prospectus registered with MAS, and you can only skip that if you stay inside a few narrow limits, no more than 50 lenders in any 12-month period, no more than $5 million raised in that window, or the offer restricted to accredited investors who are presumed to know what they’re getting into.
I want to be upfront that I’m not a lawyer, and I haven’t seen anyone officially classify Lim’s arrangement one way or the other, the case is still under investigation. But look at the shape of the business. Collecting up to $4 million from 40+ people, raised over three years. The fund raising probably stopped because of the need to register with MAS.
When dealing with unregulated persons, MoneySense encourages individuals to ask the following questions:
- How are the profits generated? Is the return being paid from new in-flows of money or from returns from actual investments? What is the maximum I can lose?
- How long must I stay invested? What happens if I withdraw my money? What are the penalties, restrictions and procedures?
- What are my options for recourse if anything goes wrong?
If Lim’s investors had asked those questions and pushed for a straight answer, I doubt many of them would have felt comfortable moving forward.
This isn’t a small detail. Investment scams were the costliest category of scam in Singapore in 2025, ahead of every other type, precisely because they’re built to survive a casual conversation. The unregulated deal that comes to you through a friend, or a Facebook community, doesn’t feel like a scam in the moment. It feels like you got in early.
Guaranteed Returns Are Usually The Red Flags
I want to be precise here, because it would be easy to walk away from this story thinking vending machine businesses themselves are the problem. They’re not. A well-placed, well-run machine can realistically produce a 20 to 40 per cent net margin. That’s a genuinely decent business.
The problem is that a genuine business with those margins doesn’t need to guarantee you a fixed return regardless of how it performs. Real operating businesses have good months and bad ones. One of Lim’s investors had a machine placed outside his workshop that worked for three days out of five months, and he was still promised the same fixed payout as everyone else. When an operator guarantees you a return no matter what actually happens on the ground, ask yourself who’s absorbing the difference. In arrangements like this, it’s usually the next batch of investors’ capital, right up until it isn’t.
If someone can promise you a fixed number regardless of performance, that’s not confidence in the business.
That’s the red flag that you should be worried about.
Why a Financial Adviser Still Fell for It
This is the part I keep coming back to. Lin’s own explanation for why he felt comfortable was: “I felt that the risks were low because he seemed to be a good guy, and a family man with five kids. And this is Singapore, where can you run?” That’s not a competence failure. A qualified financial adviser should know what due diligence looks like. But he ignored it anyway.
Look at how the trust actually got built. Kevin met Lim through mutual connections in a Facebook community, and later arranged to meet him. And for over two years, the payouts arrived on time. That track record did a lot of work.
But in arrangements like this, early payouts aren’t really proof the business works, they’re often just other investors’ capital being recycled back out to build exactly this kind of confidence.
From Kevin’s perspective however, two years of a monthly deposit hitting his account may have looked indistinguishable from a real, working investment. I think this is where his professional instincts actually misfired rather than switched off. He would have known how to read a contract, a fixed rate, and a monthly payment schedule, because that’s the format of the regulated products he sells every day. He applied his trust in that familiar format to a deal that had none of the substance behind it.
Then came the part I find hardest to read past. By August 2024, Lin had borrowed $291,322 across four separate bank loan agreements specifically to put more money in. I want to sit on this, because it’s the single worst decision in the whole story, and it’s a mistake anyone reading this could make in a smaller way.
A bank loan doesn’t care what happens to your investment. You owe the principal and the interest on a fixed schedule regardless of whether Nozomii ever pays you a cent.
When you borrow to invest, the money you’ve borrowed needs to outperform the cost of borrowing just for you to break even, and worse, you’ve removed your own margin of safety.
If the investment goes to zero, you don’t just lose paper gains you never really had, you’re now in real debt for money that no longer exists anywhere. That’s what happened here. When the payouts slowed in February 2026 and then stopped, Lin wasn’t just out his original capital, he was still on the hook to the bank for $291,322, with nothing left to show for it.
Compare that to leverage used well, a mortgage on a property that generates rental income, or a margin loan against a liquid, diversified portfolio you can monitor daily and exit if things turn. Both of those give you visibility and an exit. What Lin did was borrow into an illiquid, unsecured, single-counterparty arrangement he couldn’t verify and couldn’t easily walk away from. That’s leverage applied to the one situation where it does the most damage when things go wrong.
Here’s What I Take Away From This
Strip away the Lamborghini, the Audi R8, and the “financial adviser” distraction, and what’s left is the same mechanical structure behind almost every bad money (I’m not calling it Ponzi because the case is still under investigation) scheme that’s ever collapsed in Singapore. Unless there’s black and white proof that the profits you are receiving is from business revenue, always assume that the money comes in from a portion of the money from new participants.
As long as new money keeps arriving faster than old money needs to be paid out, the whole thing looks exactly like a functioning business. The moment new money slows down, even a little, the payments stop, because there was never enough real underlying profit to cover them in the first place. That’s not a business hitting a rough patch. That’s the scheme running out of runway.
Every red flag in this story is really just a symptom of that one structural fact. A fixed return that doesn’t move with how the machines actually perform, that’s a return with no real link to a real business. It doesn’t matter who’s selling it. It would have failed in exactly the same way.
So the question that actually protects you isn’t “do I trust this person.” It’s “does this arrangement need new money to keep flowing in for my return to keep arriving.” If the honest answer is yes, this is not an investment.